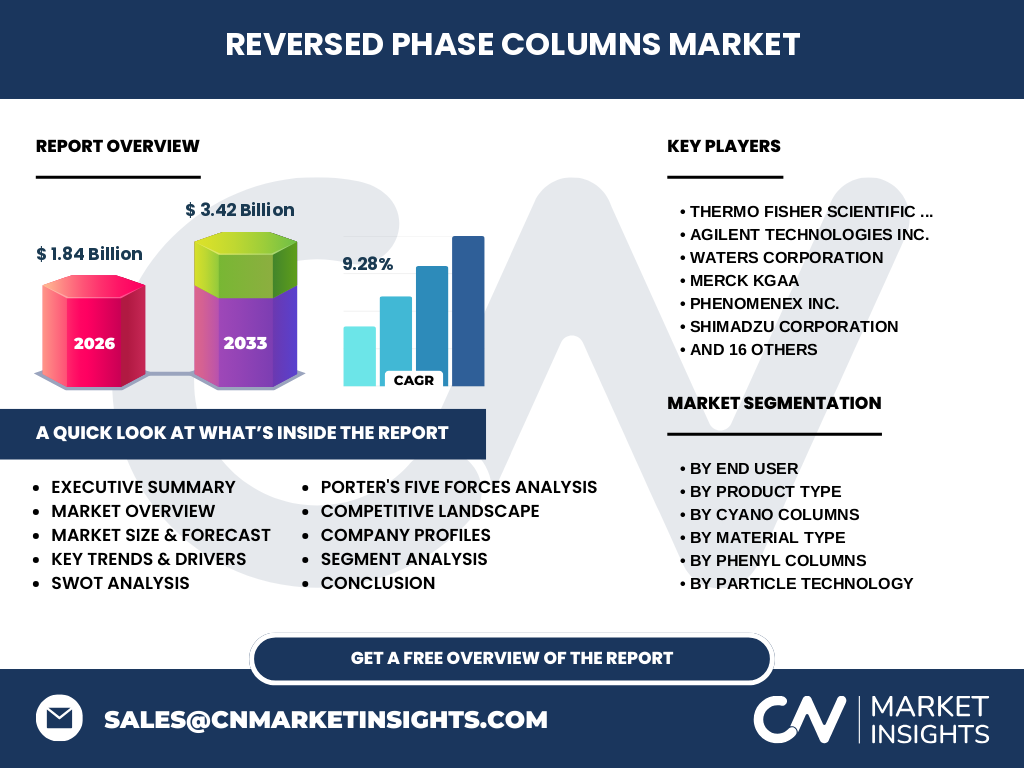
Market overview of the Reversed Phase Columns Market
Our analysis indicates that the Reversed Phase Columns Market represents a cornerstone of modern analytical chromatography. Valued at 1.84 Billion in 2026, this sector provides essential stationary phases for high-performance liquid chromatography. Industry significance stems from its critical role in separating complex biomolecules, small-molecule pharmaceuticals, and environmental pollutants in compliance with USP and ICH guidelines.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by surging biologic drug approvals and strict FDA purity standards. Primary restraints include volatile silica raw material costs and stringent supply chain hurdles. Key opportunities lie in developing core-shell superficially porous particles that enhance separation efficiency without escalating backpressure for laboratories globally.
Emerging trends and growth patterns in the industry
The shift toward green chromatography and miniaturized columns dominates current industry trends. Laboratories increasingly demand sub-2-micron fully porous particles and polar embedded phenyl chemistries to resolve complex chiral compounds. Leading innovators like Waters Corporation and Agilent Technologies Inc. are pioneering ultra-inert surface technologies to eliminate secondary silanol interactions.
COVID-19 impact analysis and recovery trajectory
The pandemic initially triggered severe supply chain bottlenecks for ultra-pure silica gel and titanium hardware components. However, subsequent vaccine development and monoclonal antibody production catalyzed a rapid demand surge. Our research shows that post-pandemic biopharmaceutical investments permanently accelerated adoption rates across contract research organizations.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration among multinational analytical instrument titans like Thermo Fisher Scientific Inc. and Shimadzu Corporation, alongside specialized separation specialists like Phenomenex Inc. and Restek Corporation. Strategic dynamics hinge on proprietary bonding chemistries and endcapping technologies that differentiate performance in demanding peptide mapping assays.
Executive summary of the Reversed Phase Columns Market report
Our executive synthesis reveals robust market momentum driven by biopharmaceutical expansion and automated analytical workflows. The Reversed Phase Columns Market industry trends point toward a high-growth trajectory, expanding from 1.84 Billion in 2026 to 3.42 Billion by 2033 at a notable CAGR of 9.28%.
Market forecast from 2027 to 2033
Projected growth indicates the market will surge from 1.84 Billion to 3.42 Billion by 2033, expanding at a robust 9.28% CAGR. This expansion is sustained by escalating research expenditure in proteomics, metabolomics, and routine quality control testing across emerging Asian economies.
Segmentation analysis by end user, product type, and material
Segmentation is categorized by end user, product type, and material. End users include pharmaceutical companies, contract research organizations, and food testing labs. Product types feature octyl silica, butyl silica, phenyl, and cyano columns. Material types span silica gel columns, polymer-based columns, and composite columns, catering to diverse pH stability requirements.
Regional market analysis and geographic distribution
Geographic performance highlights North America as the revenue leader due to dense biopharmaceutical clustering and stringent EPA environmental mandates. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, fueled by expanding contract manufacturing footprints in India and advanced life science investments in Japan.
In-depth regional review of key markets
North American growth is underpinned by extensive FDA regulatory oversight necessitating high-reproducibility stationary phases. In contrast, European markets focus heavily on REACH-compliant environmental testing agencies. The Asia-Pacific region capitalizes on cost-effective raw material sourcing and rapidly modernizing clinical diagnostic laboratories.
Company profiles and strategic positioning
Key market participants such as Merck KGaA, Tosoh Corporation, and Daicel Corporation maintain dominant positions through aggressive patent portfolios in particle technology. Specialty players like YMC Co. Ltd. and Imtakt Corporation carve out profitable niches with proprietary mixed-mode and specialized polar-embedded stationary phases.
Porter's Five Forces analysis
Industry rivalry is intense, dominated by established multinational titans with vast distribution networks. Bargaining power of suppliers is moderate, constrained by the specialized requirement for high-purity spherical silica. Threat of substitutes remains low due to the unmatched resolving power of reversed-phase liquid chromatography in regulatory-compliant assays.
SWOT analysis of the Reversed Phase Columns industry
Strengths include high analytical precision and indispensable status in drug discovery. Weaknesses involve high column cost and sensitivity to extreme pH mobile phases. Opportunities thrive in monoclonal antibody analytics, while threats emerge from counterfeit low-cost stationary phases compromising analytical integrity.
Value chain analysis from raw materials to end-users
The value chain initiates with ultra-pure tetraethylorthosilicate synthesis and high-grade stainless steel tubing manufacturing. Mid-stream processes involve proprietary surface bonding chemistry, endcapping, and slurry packing. Downstream distribution reaches pharmaceutical giants via specialized logistics networks ensuring temperature and shock-resistant transit.
Investment insights and strategic recommendations
High-potential investment areas target core-shell superficially porous particle manufacturing and polymer-based columns offering extended pH stability. Investors should prioritize partnerships with contract research organizations to secure recurring consumable revenue streams in high-throughput bioanalytical screening facilities.
Conclusion and key takeaways
The Reversed Phase Columns Market market size trajectory underscores its vital role in modern life sciences. With a forecasted expansion to 3.42 Billion by 2033, stakeholders must focus on advanced particle engineering and specialized surface chemistries to capture high-margin segment opportunities.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief chromatography officers, and secondary macroeconomic indicators. This multi-tiered approach ensures accurate sizing of specialized sub-segments like monolithic columns and core-shell technologies.
Scope of the report and coverage parameters
This report encompasses a comprehensive evaluation of the global Reversed Phase Columns Market analysis, covering all major product types, particle technologies, and end-user verticals across North America, Europe, Asia-Pacific, and Rest of World. Limitations exclude low-pressure flash chromatography consumables.
Recent developments in the industry
Recent strategic moves feature Biotage AB and Restek Corporation launching expanded lines of base-deactivated endcapped columns designed for aggressive basic pharmaceutical compounds. Concurrently, GL Sciences Inc. and Sepax Technologies Inc. have announced strategic distribution partnerships to scale their core-shell particle availability across emerging markets.